B2B Returns Management in 2026: Key Challenges and Best Practices
B2B returns management in 2026 is less about accepting unwanted goods and more about controlling a complex process across contracts, warehouses, finance, customer service, and supply chain partners. The strongest programs define return eligibility before a sale, issue authorization before transport, capture item-level evidence, route goods according to condition, and connect the final disposition to inventory and credit decisions.
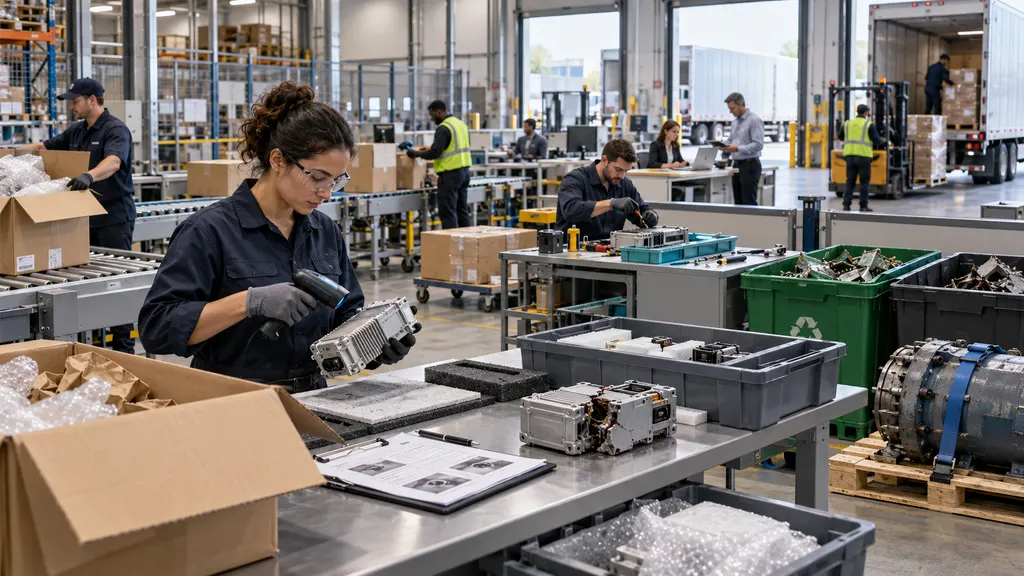
That operating model matters because a business return can involve serialized equipment, partial shipments, project-specific configurations, warranty claims, hazardous materials, international customs, or negotiated service-level agreements. A process designed for consumer parcels often cannot provide the controls that B2B buyers and suppliers need.
What B2B returns management includes
B2B returns management covers the activities that move a product from a customer back to an approved destination and determine what happens next. It normally includes:
- Return-policy and contract-rule management
- Return merchandise authorization, or RMA, creation
- Eligibility checks for warranty, defect, over-shipment, damage, recall, or commercial return reasons
- Transport instructions, labels, pickup coordination, and shipment visibility
- Receiving, inspection, testing, and evidence capture
- Disposition decisions such as restock, repair, refurbishment, replacement, recycling, or disposal
- Credit, refund, replacement, debit memo, and accounting reconciliation
- Root-cause analysis and feedback to sales, procurement, manufacturing, and fulfillment teams
The system of record may be an ERP, warehouse management system, customer service platform, dedicated returns application, or a connected combination of these systems. The technology choice is secondary to process ownership: someone must be accountable for the return from the first request through final financial and inventory closure.
Why B2B returns are difficult in 2026
1. Contract terms are not the same as a standard return policy
A B2B return may be governed by a master service agreement, purchase order, warranty schedule, distributor agreement, or project statement of work. The buyer may have a negotiated inspection period, while the supplier may reserve the right to repair rather than replace. Some products may be returnable only with prior approval, and others may require a field-service visit.
This creates a common failure point: a customer service agent approves a return using a generic rule that conflicts with the account contract. The result can be an unauthorized shipment, an avoidable restocking dispute, or a credit that finance later rejects. Effective programs translate commercial terms into clear decision rules and make exceptions visible instead of hiding them in email threads.
2. Product identity and condition are harder to verify
B2B goods often need more than a product SKU. Serial numbers, lot numbers, batch codes, configuration details, asset tags, warranty dates, and installation records may determine whether a return is valid. The condition may also matter: unopened stock, installed equipment, used components, damaged packaging, suspected counterfeit goods, and products exposed to contamination should not follow the same path.
A return workflow should therefore capture the expected item before transportation and compare it with the item received. Photos, test results, scan events, and inspection notes can provide a more defensible record than a free-text reason alone. GS1 identifies standards-based identification and data sharing as important components of traceability, which is directly relevant when businesses need to connect a returned unit to its product and transaction history.
3. Reverse logistics is often multi-party
The customer may ship to a supplier, distributor, repair center, manufacturer, or third-party logistics provider. A cross-border return may also require customs documentation, export classification, broker coordination, and a decision about whether the goods should be repaired locally or returned to the country of origin.
Visibility should not stop when a label is created. The responsible team needs to know whether the carrier collected the shipment, whether the destination received it, whether inspection is pending, and whether the financial resolution has been completed. A tracking number alone is not a returns process, but reliable shipment events can prevent avoidable customer contacts and help teams investigate delays.
4. The financial result may be unclear
A physical return and a financial credit are related but separate events. A supplier may receive goods and still reject the credit because the quantity, serial number, condition, or reason does not match the authorization. Conversely, finance may issue a credit before the warehouse has confirmed what was received.
The process should define when a credit becomes eligible, who can approve exceptions, and how freight, restocking fees, warranty obligations, taxes, and replacement shipments are handled. These rules should be agreed by operations, finance, sales, and customer service rather than designed by one department in isolation.
A practical comparison of B2B returns operating models
| Operating model | Best fit | Main strength | Main risk |
|---|---|---|---|
| Manual email and spreadsheet process | Low volume and highly unusual returns | Flexible to start | Poor auditability, inconsistent decisions, and weak status visibility |
| ERP-led workflow | Returns closely tied to orders, inventory, and finance | Strong transaction control | Customer-facing workflows and carrier exceptions may need additional tools |
| Dedicated returns platform | Multiple channels, locations, or return reasons | Structured authorization, routing, and communication | Integration and data-governance work are still required |
| Outsourced reverse logistics | Distributed facilities or specialist inspection needs | Access to operational capacity and expertise | Less direct control unless service levels and data access are explicit |
This is not a ranking. A manufacturer with serialized products may need an ERP-centered process plus specialist repair operations. A distributor with many suppliers may benefit more from a shared authorization and visibility layer. A small business can begin with controlled forms and approvals, but should define the data model before transaction volume makes migration difficult.
Best practices for building a reliable process
Start with a return taxonomy
Do not use one broad reason such as “customer return.” Separate commercial returns, warranty claims, transport damage, wrong item, over-shipment, quality failure, recall, end-of-life recovery, and repair requests. Each category should have an owner, eligibility rule, evidence requirement, destination, and financial treatment.
Keep the list usable. Too many nearly identical reason codes reduce data quality. The goal is to distinguish decisions that change the next action, not to create a detailed vocabulary that employees avoid.
Use RMA approval as a control point
An RMA should identify the customer, order or contract, item, quantity, reason, expected condition, return location, shipping responsibility, and approval status. For high-value or regulated goods, add serial or lot information and required documents. The authorization should also state what happens if the received item does not match the request.
Avoid treating an RMA number as automatic proof that a credit is owed. It authorizes a movement and inspection process; the final commercial resolution may depend on the receiving result and contract terms.
Design disposition before the item arrives
A warehouse should not have to invent a destination after inspection. Define disposition paths in advance, including restock, quarantine, repair, refurbishment, supplier return, parts recovery, recycling, and disposal. The right path may depend on condition, resale value, warranty status, safety, data security, and local regulations.
For equipment that stores customer data, disposition rules should include data-erasure or chain-of-custody requirements. For products subject to safety, environmental, or transport controls, involve qualified compliance personnel rather than treating the return as ordinary inventory.
Connect shipment visibility to case status
Customers and internal teams need business milestones, not only carrier scans. Useful statuses include return requested, approved, label issued, in transit, received, inspection pending, inspection completed, resolution approved, credit issued, replacement shipped, and closed.
A multi-carrier tracking layer can support this visibility when returns move through different transport providers or countries. The business should still define how raw tracking events are translated into operational statuses and what happens when an event is missing or contradictory.
Measure the complete cycle
A single average return time can conceal the real bottleneck. Measure at least the time from request to approval, approval to dispatch, dispatch to receipt, receipt to inspection, inspection to resolution, and resolution to financial closure. Also monitor unauthorized returns, repeat contacts, unmatched receipts, aging RMAs, recovery value, and the share of returns with a usable root cause.
Targets should reflect the product and contract. A routine consumable return and a complex industrial repair should not be judged against the same clock. Segment results by customer, product family, return reason, carrier, facility, and supplier before changing policy.
How to choose and validate a returns solution
Before selecting software or an external provider, map one normal return, one exception, and one high-risk return from request to closure. Then test whether the proposed solution can:
- Apply different rules by account, contract, product, country, and reason
- Capture serial, lot, quantity, condition, and evidence data
- Support multiple return destinations and carrier services
- Exchange status and financial data with the ERP, WMS, CRM, or order system
- Keep an audit trail of approvals, edits, inspections, and credits
- Handle partial returns, replacements, exchanges, and split shipments
- Expose data for aging, root-cause, recovery, and customer-service reporting
Ask vendors to demonstrate the exception path, not only the standard label workflow. Require a test using realistic data and define who owns integration failures, carrier exceptions, data retention, and customer communications. A polished front end cannot compensate for missing inventory or finance controls.
A 2026 planning checklist
- List every return type and the contract or policy that governs it.
- Assign a process owner for each stage, including financial closure.
- Standardize the minimum data set for authorization, receipt, inspection, and disposition.
- Separate shipment status from approval, inspection, and credit status.
- Document special handling for cross-border, hazardous, serialized, regulated, and data-bearing products.
- Set exception rules for mismatched quantity, unauthorized shipments, and damaged goods.
- Review carrier, warehouse, supplier, and repair-partner performance by return segment.
- Run a quarterly root-cause review and feed findings into product, packaging, sales, and fulfillment decisions.
Final judgment
The best B2B returns program is not necessarily the one with the most automation. It is the one that makes commercial rules, physical handling, evidence, customer communication, and financial decisions agree. Automation is valuable when it removes repeated manual work and makes exceptions visible. It is risky when it hides an unclear policy or pushes incomplete data into the ERP.
For most organizations, the sensible sequence is to establish the return taxonomy and ownership model first, connect authorization with inventory and finance second, and then optimize carrier visibility, routing, and disposition. That sequence produces better decisions than buying a tool before the business has defined what a successful return actually means.
FAQ
What is the difference between B2B and consumer returns management?
B2B returns are more likely to depend on negotiated contracts, purchase orders, serial numbers, warranty terms, inspection results, partial shipments, and financial reconciliation. Consumer returns can also be complex, but B2B workflows usually require stronger account-level controls and more detailed evidence.
Is an RMA always required for a business return?
Not always. The requirement depends on the contract, product, supplier, and operating model. However, an approval record or equivalent control is useful whenever the business must verify eligibility, route goods, protect inventory accuracy, or determine credit responsibility.
Which metrics should a B2B returns team track?
Useful measures include approval time, transport time, receiving-to-inspection time, inspection-to-resolution time, financial closure time, aging RMAs, unmatched receipts, repeat contacts, recovery value, and return reasons by product and customer. Segmenting these measures is more informative than relying on one overall average.
Should returns be managed in the ERP or in a separate platform?
An ERP is often the financial and inventory authority, while a separate platform may provide more specialized customer, carrier, routing, or exception workflows. The appropriate design depends on transaction complexity and existing systems. The critical requirement is a reliable exchange of authorization, receipt, disposition, and credit data.
How should companies handle information that is not publicly documented by a software vendor?
Treat it as a procurement question rather than an assumed capability. Request documentation, a product demonstration, security and integration details, and a test using representative return scenarios. “Not publicly stated” does not prove that a feature is unavailable.
Sources
- GS1, Traceability Standards — identification and traceability principles relevant to returned products.
- SAP, Returns Management — enterprise returns-process concepts and system context.
- Oracle, Returns Management — returns orchestration and supply-chain workflow context.
- Your Europe, Guarantees and Returns — official European consumer-return guidance, included to distinguish consumer rules from negotiated B2B terms.
- Uniform Law Commission, Uniform Commercial Code — reference point for the commercial-law framework in the United States; specific contractual advice requires legal review.


